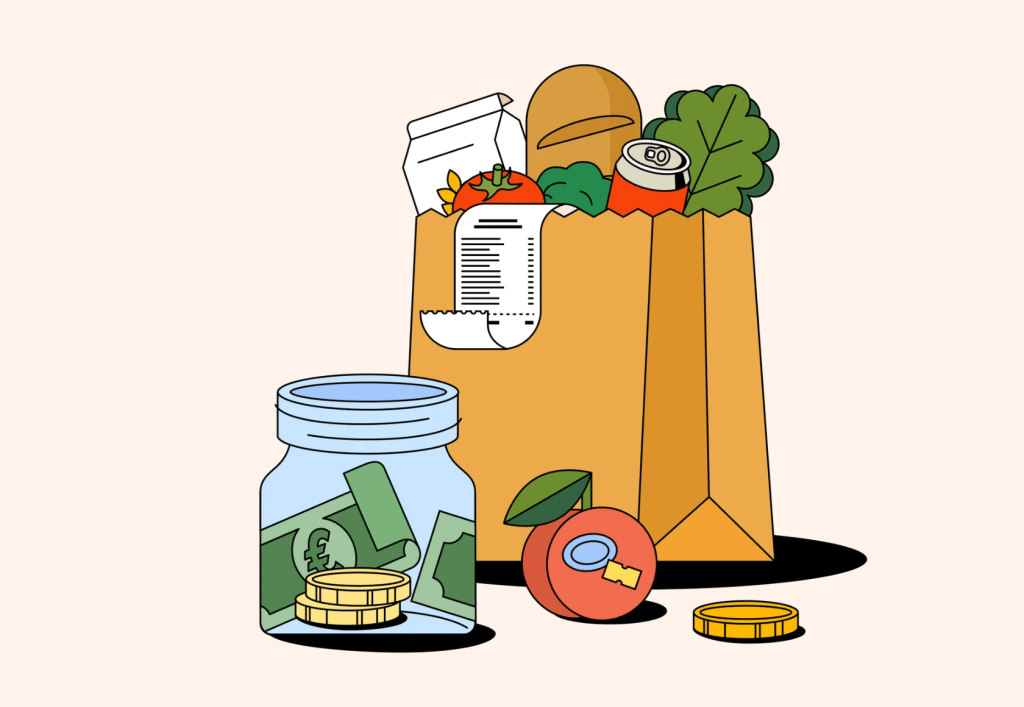
The Consumer Price Index (CPI) is a statistical measure that tracks the average change in prices of a basket of goods and services consumed by households. It’s a widely followed indicator of inflation, which is the rate at which prices for goods and services are rising. The CPI is published monthly by the Bureau of Labor Statistics (BLS), a unit of the U.S. Department of Labor.
How is the CPI Calculated?
The CPI is calculated by collecting prices for a representative sample of goods and services from over 23,000 retail establishments across the United States. The BLS uses a complex formula to weight the prices of these items, reflecting the average expenditure patterns of urban households. The CPI basket includes:
- Food and beverages (14.3% of the total weight)
- Housing (44.1% of the total weight)
- Apparel (2.4% of the total weight)
- Transportation (17.2% of the total weight)
- Medical care (8.3% of the total weight)
- Recreation (5.1% of the total weight)
- Education and communication (5.7% of the total weight)
- Other goods and services (2.9% of the total weight)
CPI vs. Core CPI
Headline CPI includes everything, including food and energy, the two most volatile categories. Core CPI strips them out. Economists prefer core because a gasoline spike or a bad harvest tells you nothing about underlying price trends. The Federal Reserve goes one step further: it sets policy against core PCE inflation, a different index it considers better behaved, not CPI. When the news says inflation is cooling but your grocery bill disagrees, the gap is usually food and energy.
CPI in 2026
Through August 2026, headline CPI is running about 3.4% year over year, still above the Fed’s 2% target. The composition matters: energy is up roughly 16.3% over the year (gasoline about 27.4%), while core inflation, everything except food and energy, is around 2.4%. Inflation is not one number hitting everyone equally; it is an average that hides very different experiences by category.

Why Does the CPI Matter to Your Personal Finances?
The CPI has a significant impact on your personal finances, as it influences:
- Inflation expectations: A rising CPI indicates increasing inflation, which can erode the purchasing power of your money. This means you may need to adjust your budget to account for higher prices.
- Interest rates: The Federal Reserve, the central bank of the United States, uses the CPI to inform its monetary policy decisions, including setting interest rates. Higher inflation can lead to higher interest rates, affecting borrowing costs and savings rates.
- Cost-of-living adjustments: The CPI is used to calculate cost-of-living adjustments (COLAs) for Social Security benefits, pensions, and other government programs. A higher CPI can result in higher benefits to keep pace with inflation.
- Investment decisions: Understanding the CPI can help you make informed investment decisions, as certain assets (e.g., Treasury Inflation-Protected Securities, or TIPS) are designed to protect against inflation.
Chained CPI: The Substitution Argument
The standard CPI measures a fixed basket of goods. Critics have long argued that this overstates the cost of living, because people substitute: when beef prices jump, households buy more chicken, and the fixed basket misses the trade. Chained CPI (C-CPI-U) accounts for that substitution, and it typically runs about 0.25 to 0.3 percentage points lower per year than headline CPI. The distinction has real consequences. Since the 2017 Tax Cuts and Jobs Act, federal income tax brackets have been indexed to chained CPI rather than standard CPI. Slower bracket growth means more bracket creep over time, which is exactly why the choice of index was worth fighting over. Two measures of inflation, a quarter point apart, and your tax bill notices.
The CPI Number That Lands in Your Paycheck
For most households, the CPI that matters is not the headline on the news. It is the one wired into contracts. Social Security cost-of-living adjustments are tied to CPI-W, a related index for wage earners. Run the numbers: a 2.4% COLA on a $2,000 monthly benefit adds $48 a month, or $576 a year, before any Medicare premium increase eats into it. Union contracts, pensions, and plenty of commercial leases carry similar escalators. This is why inflation statistics are never just academic. Somewhere in the fine print of your income, a CPI number is doing arithmetic on your behalf, and it pays to know which one.
Key Takeaways
- The Consumer Price Index (CPI) measures the average change in prices of a basket of goods and services consumed by households.
- The CPI is a widely followed indicator of inflation, published monthly by the Bureau of Labor Statistics (BLS).
- The CPI has a significant impact on your personal finances, influencing inflation expectations, interest rates, cost-of-living adjustments, and investment decisions.
- Your personal inflation rate depends on your spending mix. If housing is 44% of the CPI basket but 25% of your budget, the official number overstates what you feel.






You must be logged in to post a comment.