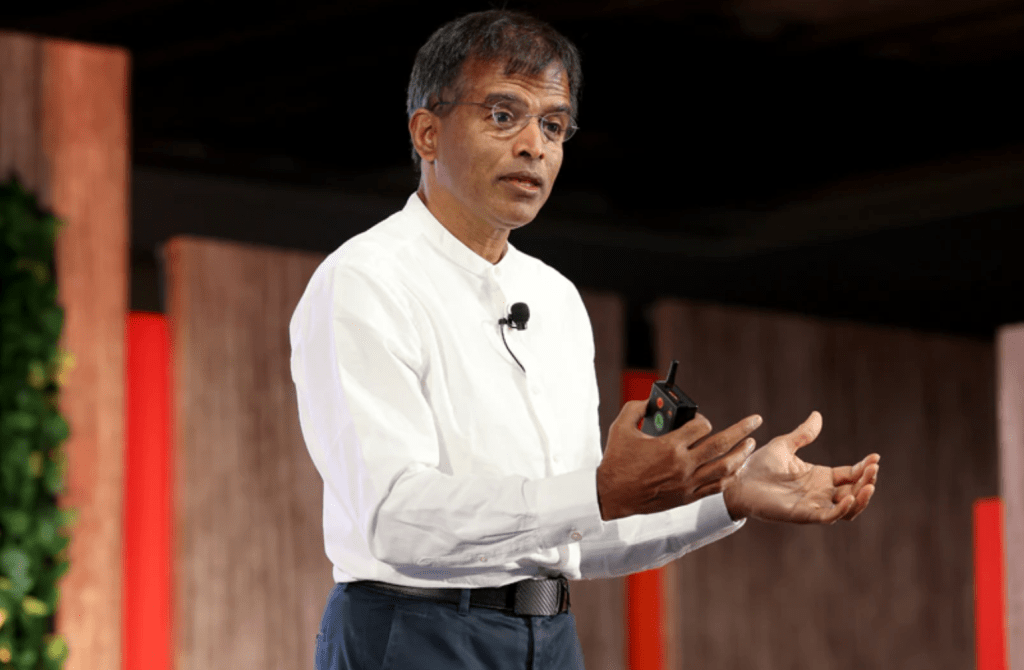
Born in 1957 in Chennai, India, Damodaran received his MBA and Ph.D. from the University of California, Los Angeles. He joined NYU’s Stern School of Business in 1986 and has since become one of the most respected voices in finance.
Key Contributions
Damodaran’s work focuses on the practical applications of finance, making complex concepts accessible to a broad audience. Some of his notable contributions include:
- Valuation frameworks: Damodaran has developed and refined various valuation models, including the Discounted Cash Flow (DCF) model, the Comparable Companies Analysis and the Precedent Transactions Analysis.
- Cost of capital: His work on estimating the cost of capital, including the Weighted Average Cost of Capital (WACC), has become a standard reference for finance professionals.
- Country risk premiums: Damodaran’s research on country risk premiums has helped investors better understand and quantify the risks associated with investing in emerging markets.
- Valuation of intangibles: He has written extensively on the valuation of intangible assets, such as brand name, patents and trademarks.

Impact and Legacy
Aswath Damodaran’s work has had a profound impact on the field of finance, influencing:
- Investment analysis: His valuation frameworks and cost of capital estimates are widely used by analysts and investors.
- Corporate finance: Damodaran’s research has shaped the way companies approach capital budgeting, financing and risk management.
- Academia: His teaching and research have inspired a new generation of finance scholars and practitioners.
Aswath Damodaran’s contributions to finance have been instrumental in shaping the way we think about valuation, corporate finance and risk management. His work continues to inspire and educate finance professionals, investors and students around the world. By understanding and applying his insights, we can make more informed decisions and navigate the complex world of finance with greater confidence.
Books by Damodaran
Damodaran has authored several influential books, including:
- Damodaran on Valuation (1994) – A comprehensive guide to valuation techniques and applications.
- Applied Corporate Finance (1999) – A textbook that bridges the gap between theory and practice in corporate finance.
- The Dark Side of Valuation (2001) – A critical examination of valuation practices and pitfalls.
Free Online Investing Lessons
Damodaran makes most of his investing lessons available online either through his YouTube channel or his personal website.
About the Video: Introduction to Valuation
The embedded video is Damodaran’s “Introduction to Valuation,” the opening lesson from the valuation course he teaches at NYU Stern and shares free on YouTube. In it he makes the case that there are three, and only three, ways to value an asset: intrinsic valuation, relative valuation, and options pricing.
Intrinsic valuation, usually done with a discounted cash flow model, asks what an asset is worth based on the cash it will generate. Relative valuation, or pricing, asks what similar assets are selling for and assumes the market gets the average right. Options pricing applies when an asset has option-like features, such as undeveloped land or a patent. Most of what passes for valuation on television is relative valuation, which is why markets can be wrong together: pricing works until the whole market is mispriced.
His deeper point is that every valuation is biased. The analyst chooses the inputs, and the inputs reflect a story about the future. Damodaran’s remedy is to make the story explicit: if you cannot tell the story behind your numbers, your numbers are not worth much. The video is short and dense, and it rewards a second viewing with a notebook.
Popular videos include
Why an Index Investor Should Still Learn Valuation
Most readers of this site will never build a discounted cash flow model, and that is fine. An S&P 500 index fund does not require you to value anything. But valuation literacy still pays.
First, it explains market moves. When a stock with no earnings doubles, you will recognize relative valuation at work: investors are pricing it against other hot stocks, not against its cash flows. Second, it disciplines expectations. Damodaran’s insistence that price and value are different things is the intellectual backbone of index investing itself: since even professionals struggle to separate the two, owning the whole market at low cost is the rational response. Third, it tames panic. Understanding that a 20 percent market drop usually reprices the same cash flows, rather than destroying them, makes it easier to hold through the scary months.









 Winchell House

You must be logged in to post a comment.