Book Summary
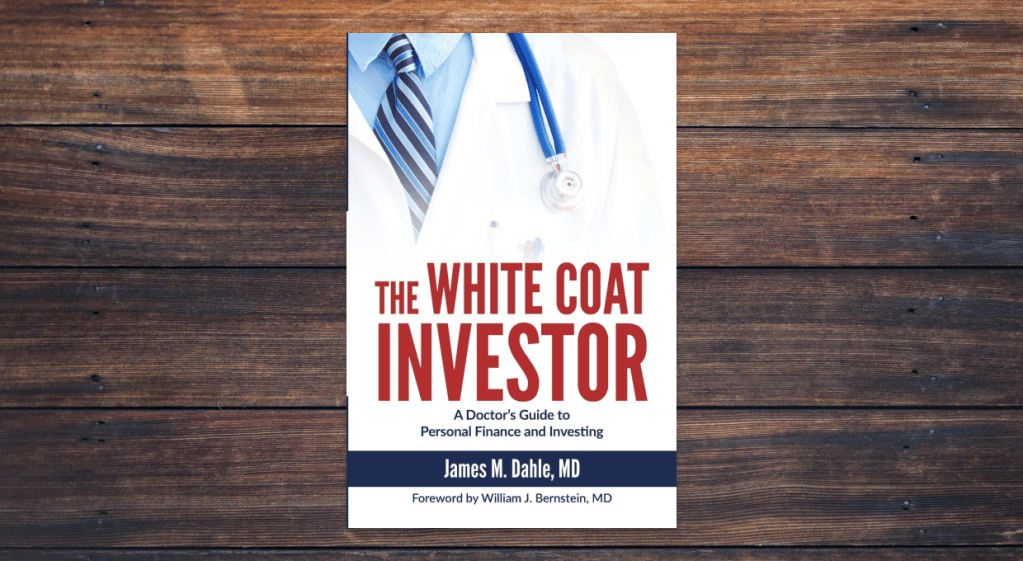
The White Coat Investor is James Dahle’s plain-English manual for a group that earns a lot of money and manages it badly: physicians. Published in 2014, the book runs a tight sixteen chapters and makes one central argument — doctors don’t have an income problem, they have a financial-education problem, and the people who step in to “help” usually have something to sell. Dahle’s answer is a complete framework: write a financial plan, keep living like a resident after training ends, insure your income properly, invest in low-cost index funds, and use the tax code instead of fighting it. It is short, direct, and free of jargon, the way a good attending explains something on rounds.
Who is James Dahle?
James M. Dahle, who goes by Jim, is a practicing emergency medicine physician. He started The White Coat Investor as a blog in 2011 after a string of bad experiences with commission-driven financial salespeople, and it has since grown into the most widely read physician-focused personal finance site in the world. He is the author of several books — including the follow-up The White Coat Investor’s Financial Boot Camp — hosts two weekly podcasts, and runs an annual financial literacy conference for doctors. He writes like someone who learned this material the expensive way and would rather you didn’t.
Lessons From The White Coat Investor
Live like a resident. The most important years of a physician’s financial life are the first few after training, when income jumps several-fold overnight. Dahle’s flagship advice is to bank that raise instead of spending it — keep the resident lifestyle a little longer and the compounding does the rest. Lifestyle inflation is the silent killer of high incomes.
Insure your income before anything else. For a doctor, the greatest asset isn’t a portfolio, it’s the ability to earn. Dahle puts own-occupation disability insurance at the top of the shopping list, bought individually rather than relied on through an employer, plus term life insurance for anyone with dependents. He walks through policy terms so readers actually understand what they’re buying.
Learn how your advisor gets paid. A recurring theme of The White Coat Investor is that much of the financial advice aimed at doctors is salesmanship — whole life insurance and high-fee products pushed by people earning commissions. Dahle teaches readers to spot conflicts of interest, and to either hire a flat-fee fiduciary or manage things themselves.
Keep investing boring. The investing advice is deliberately unsexy: low-cost passive index funds, diversified across asset classes, contributions automated, no market timing, no chasing hot funds. Dahle’s point is that busy professionals don’t need a clever strategy, they need a durable one they will actually stick with.
Use the tax code. Maxing out 401(k)s, IRAs, and HSAs, understanding asset location, and planning around taxes — Dahle treats tax efficiency as a genuine source of return, not an afterthought. For high earners in high brackets, this chapter alone can pay for the book many times over.
Write the plan down. Underneath all the tactics is a behavioral message: emotional discipline and a written financial plan matter more than technical knowledge. Physicians are used to being experts, which makes them overconfident novices with money. The book’s checklists and chapter-end action items exist to fight that.
Criticisms of the Book
The White Coat Investor is deliberately a mile wide and an inch deep, and readers should know that going in. It will not teach you which specific funds to buy or how to evaluate an active manager — Dahle points you to further reading at the end of each chapter instead, which is honest but means advanced investors will outgrow it fast. The tax, insurance, and legal material is US-specific, so international readers will need to translate. And while the principles generalize, the book is written for high-income professionals; if you’re early in a modest-earning career, some chapters won’t apply to you yet. Finally, the index-fund orthodoxy is total — if you wanted a serious treatment of active management or alternatives, look elsewhere.
Who is This Book For?
Medical students, residents, and fellows are the bullseye — the earlier this framework gets installed, the more it compounds. Practicing physicians and dentists who never got a financial education will find it immediately useful, as will other high-income professionals (lawyers, executives, tech workers) facing the same lifestyle-inflation trap. It’s also a good gift from a financially savvy parent to a kid starting residency. If you already run a tight Boglehead-style portfolio and have your insurance sorted, you’ll find it basic — but you’ll probably still nod along.
Final Thoughts
The White Coat Investor is the rare personal finance book that knows exactly who it’s for and refuses to waste their time. It won’t make you a sophisticated investor, but that was never the job — the job is keeping high-earning professionals from sabotaging themselves, and on that score it’s excellent. Short, actionable, and written by someone who has seen every way doctors lose money. For its intended reader, it’s close to essential.











You must be logged in to post a comment.